Amanda Burns

About Amanda Burns
Posts by Amanda Burns:
Impact of Government budget on conveyancing market
Whenever there are Government budgetary announcements there is, naturally, a fallout on the housing market, the consequences of which are borne by house buyers and sellers alike, and those of us working in the conveyancing market.
And it’s been a dramatic few months for such budget announcements, with significant affects now on the property market.
Here, we take a look at the recent changes and announcements, of the Autumn Statement and implications of what may lay ahead in terms of issues and impacts affecting conveyancers and the property market for 2023.
Truss’s short-lived premiership and economic disruption
Liz Truss’ premiership, although short-lived, brought seismic changes and disruption to the conveyancing and property market.
The Government introduced substantial stamp duty land tax (SDLT) cuts, described as a “crowd-pleasing move” by the Chancellor at the time, Kwasi Kwarteng, when he set the mini budget, aiming to help approximately 200,000 homebuyers.
Seen by many as help for the property market, to boost activity and help homebuyers, particularly first-time buyers, the fact that there was no time limit to the SDLT cuts was lauded.
However, the mini budget also created a state of extreme economic uncertainly that caused markets to plummet and fuelled rises in mortgage interest rates.
Stamp duty cut reversal from March 2025
While no limit on the stamp duty cut may have gone some way to offset interest rate rises for house buyers, the most recent budgetary announcements from Jeremy Hunt brought the reversal of the SDLT cuts from 31st March 2025.
SDLT cut reversal creates ‘stamp duty holiday round 2’
The stamp duty cut is now seen as a long stamp duty holiday rather than a permanent change. And, as with previous stamp duty holidays, any temporary easing that sees house buyers saving money creates an incentive to buy.
Remember the conveyancing rush we experienced during the stamp duty holiday in 2020-21?
It’s not hard to see why anyone looking to buy a house may want to take advantage of the substantial savings. The stamp duty cut means a first-time buyer’s nil-band rate increases from £300,000 to £425,000, and a home mover’s nil-rate band increases from £125,000 to £250,000. The saving for a homebuyer can be up to £6,250
With the Office for Budget Reporting anticipating housing activity to slow over the next two years as the UK enters a recession, there’s no doubt that the stamp duty holiday will go some way to spurring the market on.
2023 set to be busy for conveyancers
With the deadline of the stamp duty holiday in sight for early 2025, we predict that next year is potentially going to be the busiest time for conveyancers as homebuyers look to take advantage of the holiday.
The deadline to the SDLT cuts is also likely to drive up prices, particularly in the run up to the end date, which may well mitigate activity in 2024. For this reason, 2023 is set to be the busiest year, even with the threat of recession looming.
House prices might be lowering, but…
Sources, including the house price index from the ONS show house prices are currently the lowest they have been in two years – as high interest rates are dissuading many people from buying. And some economists predict so much as a 10 or even 20 per cent fall in prices by next year.
But, while this may seem positive, particularly for first-time buyers getting on the property ladder, the fall in house prices only takes us back to pre-pandemic house-price levels, where the average house price was 65 times higher than in 1970 but wages are still only 36 times higher.
The unlikelihood of these falls in house prices greatly fuelling the market means, potentially, buyers will be particularly incentivised by the SDLT holiday.
Steadying fixed rate deals may prompt remortgage transactions
Of those homeowners whose current mortgage deals are coming to an end within the next two years, over half (55 per cent) are on two-year fixed rate deals and 39 per cent are on five-year fixed rate deals, according to research from The Mortgage Lender, owned by Shawbrook Bank.
While the term may be long enough for borrowers to sit tight on their current deals, once those deals end, they may likely seek a further deal for the reassurance that fixed-term deals bring, particularly as the cost of those deals show signs of slowing this month.
The average cost of two- and five-year fixed rate deals has fallen this December to 5.84% and 5.67% respectively, compared to highs of 6.65% and 6.51% last month.
The pressure, for homeowners, to make finances stretch as far as possible will undoubtedly cause an influx of remortgage transactions securing reasonably priced fixed deals conveyancers may want to prepare for.
We’re here to help conveyancers
As the market prepares in 2023 to be, potentially as busy as it was in 2020-21, we are here to help conveyancers speed up client transactions with our range of conveyancing policy products.
Policies, such as a ‘no search lender’, and other lender-specific policies all empower you to complete on your client’s remortgage and purchase/sale transactions, smoother and faster. Our pricing is highly competitive with the ease of use of our consumer-friendly portal.
No wait – conveyancing policies are available now
We’re able to quote a premium for you in seconds and issue policies in minutes. What would otherwise be a time-consuming transaction is rapidly taken care of.
Please view our full range of conveyancing indemnity products here.
Alternatively, get in touch on 0800 524 4235 to speak to us directly about how we can help you with faster conveyancing, or email us at info@prosperityinsurance.co.uk.
The dramatic rise in social housing disrepair claims
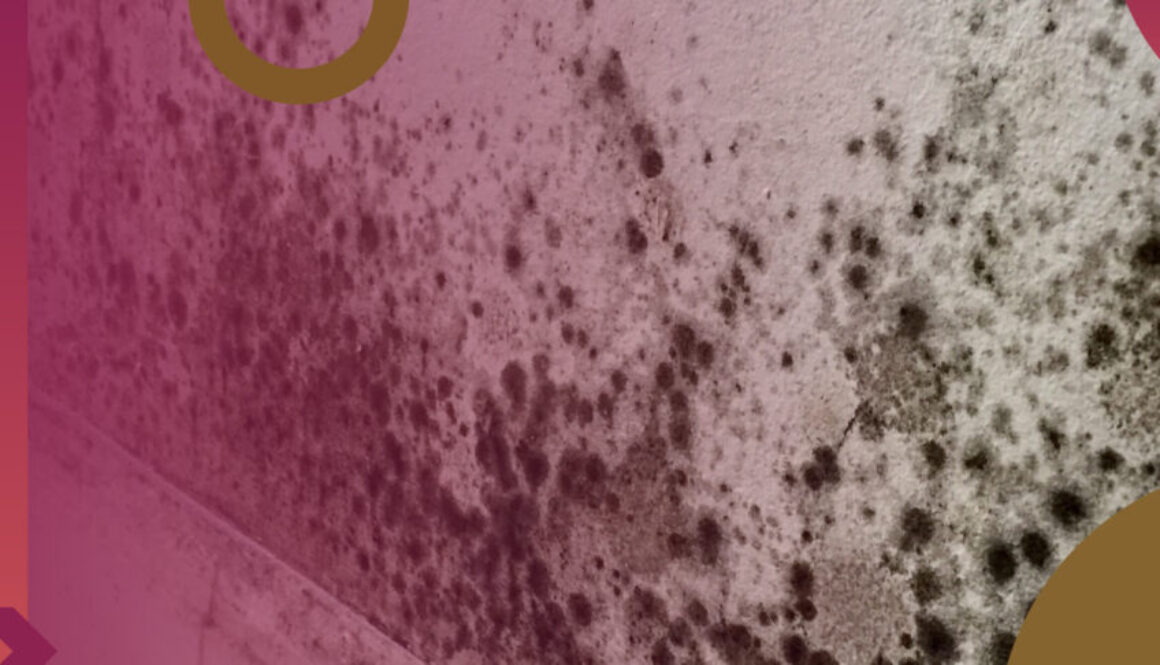
Every tenant who pays their rent when it’s due has the right to live in a property in a good state of repair. Tenants’ homes should be free of issues detrimental to health and safety, and well-being, such as dampness and mould, pest infestations, malfunctioning water and heating provision, fire hazard, drainage and flooding issues, and also structural problems.
But, in recent years, and particularly since 2017, caseloads for solicitors handling social housing disrepair claims have risen dramatically, and continue to do so.
Increase in legal grounds for complaint
The number of tenants suffering distress and inconvenience, as well as negative impacts on their health and well-being, as a result of housing disrepair is staggering, and consequently, the number of cases of those with rightful, legal grounds for disrepair claims keeps on climbing.
Councils’ legal costs double in four years with a 132% rise in cases
Local authorities’ rising legal costs for social housing disrepair claims are nationwide. Figures, gathered by Inside Housing, from 70 English councils, show a 132% increase in cases, and a year-on-year increase in costs from 2017-18, to 2020-21.
- 2017 – 2018 – £7,868,748
- 2018 – 2019 – £10,624,239
- 2019 – 2020 – £12,646,680
- 2020 – 2021 – £14,325,758
The figures represent approximately 17,000 disrepair claims with an estimated £55.1 million paid out. And this is not even the whole story, as approximately 100 local authorities did not contribute data.
One London council alone sees 600% increase in four years
Taking just one local authority alone, Lambeth London Borough Council, they stated their social housing disrepair claims increased by 600% in the last four years, with an average expense bill of £3 million a year for damages, opposition legal fees and their own defence costs.
What’s behind the surge in social housing disrepair claims?
There are many contributing factors to the dramatic rise in cases, creating a perfect storm for local authorities in meeting the legal resource and costs to deal with the continuing increase in the numbers of tenants with grounds for complaint.
Only this year, the Government declared a “backlog of need” among those currently in unsuitable accommodation, indicating the starkness of the situation, and going some way to explain the sheer number of tenants seeking legal address and therefore the knock-on effect for the legal industry.
Lack of Government funding for social housing
A root cause of the surge in housing disrepair claims is commonly acknowledged to be the impact of years of underfunding in social housing and the ensuing lack of routine repairs, maintenance and modernisation carried out. Homes have been left neglected with issues for tenants going unaddressed. Outside of the Decent Homes Programme there has been very little funding allocated to council housing stock, and, in fact, the last push for council housing was seen during the post-war era.
Rising costs of repairs
The National Housing Federation (NHF) recently issued a warning that costs for new homes, repairs and maintenance are all rising above inflation, posing challenges for many social landlords. Inflationary pressures, labour and material shortages, as well as global supply chain issues, have all led to a 33% decrease in investment in major repairs across the sector.
Scrapping of Legal Aid in 2013 for housing disrepair claims
In 2013, Legal Aid for housing disrepair claims was scrapped, unless it was for a case where the disrepair is so severe it poses a risk to tenants’ wellbeing.
The rules for Legal Aid, were acknowledged to be stringent, prior to the scrapping, which provided a filter for spurious claims coming to court. Now that the legal aid has gone for most cases, there has been an inevitable growth in no-win-no-fee cases and CFA (Conditional Fee Arrangement) work, however, many solicitors still say around eight of ten cases now coming through are genuinely valid claims.
Homes (Fitness for Human Habitation) Act 2018
When the 2018 Homes Act came into force in March 2020, it shone a spotlight on tenants’ rights, giving them the power to take legal action against landlords. The new Homes (FHH) Act opened the floodgates for claims against private landlords and could very likely have had an impact in shifting tenant focus to these claims.
The Jackson Reforms of 2013
The ‘Jackson Reforms’, named after Lord Justice Rupert Jackson, the judge who proposed them, brought a wave of reforms to the personal injury market in 2013. The most significant of the reforms was a cap on legal fees at 25%, and also that the fees now come from damages paid to the claimant, rather than the losing party. However, there is no such cap, or limit, on housing disrepair claims, which many says has exacerbated the rise in these types of claims.
The future of housing disrepair claims?
Although there is no movement from Government yet, Lord Justice Jackson wants to reform housing disrepair claims in line with those of the personal injury market and introduce Fixed Recoverable Costs, which would go some way to curbing so-called ‘claim farm’ type proceedings.
While the housing disrepair claim industry is acknowledged to be in need to reform, to remedy disparity in compensation amounts and legal fees, the grounds for legal recompense for tenants remain. The last English Housing Survey states there were over 75,000 ‘non-decent’ properties in the UK, pointing to the continuing lack of investment in social housing stock.
Prosperity Insurance experience in housing disrepair claims
Prosperity Insurance offers competitive deferred premium structures for all social housing disrepair claims and a wealth of experience in dealing with claims in this sector. Our contacts in the industry can mean significantly lower costs, enabling your clients to access the justice and compensation they deserve.
Please talk to us directly at 0800 524 4235 about any social housing disrepair claim, or for further information about any ATE policy. Alternatively, you can email us at info@prosperityinsurance.co.uk.
Remortgage market set to dramatically rise
Remortgage market set to dramatically rise
2022 is being dubbed ‘the year of the remortgage’ by mortgage advisors due to the rapidly rising number of homeowners seeking remortgage deals.
And the rise is set to be even steeper as FCA news states there are currently 370,000 mortgage borrowers who are able to save money by switching mortgage deals, yet are still not doing so, prompting advice to advisors to keep their eyes well and truly focused on this potential market.
Rising interest rates
In an effort to quell runaway inflation, the Bank of England increased the base rate of interest by 50 points in August, to 1.75%, the highest jump in 27 years, with further increases predicted for the rest of the year.
The increase in interest rates affects approximately two million homeowners almost immediately, even before further rate rises. Coupled with the high rate of inflation, currently 9.9%, way above the 2% mark of a healthy economy, the remortgage market is seeing a surge in homeowners eager to secure the lowest monthly repayments available to them.
In recent times many lenders have pulled out of mortgage deals due to economic uncertainty. The base rate is 2.25% but many analysts are estimating that this could rise to 6% by spring-time next year. The impact of this will undoubtedly push many people, where they can get a new mortgage offer to remortgage their property as soon as possible and secure a fixed interest rate to mitigate the financial burden that 2023 could bring.
The squeeze for homeowners
While rising interest rate rises have clearly fuelled the demand for remortgages, the cost-of-living crisis and the rising cost of housing have also played their part. Inflation, high mortgage rates and record-high home prices are chipping away at housing affordability, making it particularly difficult for first-time buyers to enter the housing market, while existing homeowners face increased pressures on their monthly budget.
Whilst the Government have reduced Stamp Duty liabilities and for first-time buyers and homebuyers generally in their recent budget, may predict that the long-term impact of this will be to cause an even further increase in house prices.
Reported drop in average monthly payment amount
In the July report by LMS, figures show that average monthly mortgage payments dropped, with 54% of borrowers increasing their loan size. The average monthly payment went down to £226 in July, from £236 the previous month. The most popular reason given by respondents was to release equity into their property and 70% of those who remortgaged took out a five-year fixed rate product.
The average interest rate on a two-year fixed-rate mortgage now stands at 4.24%, the highest rate since January 2013 and a huge increase from December 2021, when it was 2.34%.
While there may be a drop in house sales, as pressure on household finances increase, clearly there is likely to be no let up in house owners needing to lock in favourable rates, meaning the conveyancing market is set to remain buoyant with this increased need for remortgages.
Two-year fixed deals may overtake five-year fixed
And while the five-year fixed rate deals are currently the most popular, some predict that the two-year deals will overtake, due to the anticipation that rates will, at some point in the future, eventually come down.
Plus, with the swiftly-changing financial position for many homeowners, mortgage advisors could well highlight the two-year, shorter-term deal as most beneficial for remaining flexible to circumstances, as well as being a means of keeping the remortgage ‘churn’ continuously high.
Help to cope with the remortgage demand
The LMS has said that coping with this demand “will be vital for the industry” and that “borrowers, lenders and law firms… must collaborate to put appropriate solutions in place”.
Remortgage transactions often require a faster turnover than standard mortgage transactions, as borrowers want to move quickly to secure the currently ever-increasing rates. Borrowers can also secure deals in advance, by three or six months, but the speed of the transaction is still vital as availability of these deals reduces.
We’ll help with faster timescales
To speed up your clients’ remortgages, we offer a range of products suitable, specifically, for remortgage transactions.
Policies, such as a ‘No search Lender’, and other lender-specific policies all empower you to complete on your client’s remortgage transaction, smoother and faster. Our pricing is highly competitive with the ease of use of our consumer-friendly portal.
Policies are available now
We’re able to quote a premium in seconds and issue policies in minutes, meaning what would otherwise be a time-consuming transaction is rapidly taken care of.
You can view our full range of conveyancing indemnity products here. Alternatively, get in touch on 0800 524 4235 to speak to us directly about how we can help you with faster conveyancing, or email us at info@prosperityinsurance.co.uk.
Sources: https://www.express.co.uk/news/uk/1674759/plunging-pound-banks-pull-mortgage-deals-first-time-buyers
Problems since whiplash reforms raise concern over access to justice for genuine RTA claimants
Problems since whiplash reforms raise concern over access to justice for genuine RTA claimants
In May 2021, the Government brought in a series of whiplash reforms aimed at reducing the number of exaggerated and fraudulent RTA (Road Traffic Accident) whiplash claims, which were, as a consequence, causing insurance premiums to rise.
One year on, there remains significant criticism of the introduced reforms, not only with respect to the level of fraudulent claims, which remains high, but of the OIC (Official Injury Claim) service introduced, the original intention of which was intended to empower claimants without formal legal representation or LiPs (Litigants in Person) to self-serve in pursuing their claims.
The new rules from May 2021 for RTA whiplash injuries
New fixed tariffs for RTA whiplash injuries increased the limit on these claims for the small claims track from £1,000 up to £5,000. There were also fixed levels of compensation introduced and where general damages for pain, injury and amenity fail to exceed the £5,000 small claims limit, legal costs are no longer recoverable.
Using the OIC claims portal
In addition to the fixed tariffs and increase in the amount for small claims, the OIC claims portal was brought in by the Government, with the intention of empowering LiPs to pursue and resolve their claim without the need for legal representation.
The OIC system, which operates through an online portal, administered by the Motor Insurers’ Bureau, expects claimants to follow a ‘how-to’ guide or navigate the system, without the need for a lawyer.
OIC portal described as a “cautious success” overstates the efficacy
Speaking at the recent PI Futures conference in Manchester, David Parkin, Deputy Director of Civil Justice at the Ministry of Justice, claimed that the OIC system has been a “cautious success” adding that the system is easy enough to use if people chose to. But this is not the view widely shared by many professionals in the industry, and when 220 delegates at the conference were asked if they thought the system was going well, nobody raised their hand.
The OIC portal figures speak loud and clear
The most significant statistic of the OIC portal’s usage in the last year is that only 10% of the people using it are LiPs. And while there has been an overall reduction of 40% in RTA personal injury claims in the past year, it is widely accepted that this is mostly attributable to Covid, not the efficacy of the OIC system. Furthermore, Aviva reported for 2021, an insurance fraud increase of 13%, of which 60% were RTA-based, despite the whiplash reforms.
The portal is “a real cause for concern”
Industry professional, Sue Brown, Chair of the Motor Accident Solicitors Society, has termed the portal “a real cause for concern” with structural and operational inefficiencies resulting in thousands of unsettled claims now starting to clog the system. At the time of reporting, there were 185,000 active claims out of the 243,000 claims lodged since the system launched, with only 23,000 settled.
Obstacles to the OIC system
- A key obstacle to LiPs using the system is its complexity for making hybrid claims, where claimants report both whiplash, which is a compensation that is tariff-based, and other injuries, which are not. Claimants are advised in the guide to consider making a ‘valuation of their other injuries’, which has been seen by many as deterring claimant from progressing further.
- There have been detrimental effects on law firms who have stopped taking instructions on lower value claims, with some smaller firms relying on whiplash claims having to close completely.
- Although larger firms have fared better with the reforms, this has largely relied on their ability and willingness to invest in integrating the OIC system with their own online platforms, despite the smaller margins the reforms bring about. Adaptability has been key for these firms, and the availability of inhouse IT resource. For example:
- Slater and Gordon have integrated the system with MiPlatform, through which they plan on extending other legal services, still undertaking the legal work in pursuing claims for their customers.
- National Accident Law have reported a successful transition into the new processes, indicating that its customers were progressing quickly through the stages of the online portal, with medical reports being arranged, liability offers received, and an early settlement date anticipated.
Overall negative effect for claimants going forward
The reforms result in lower damages for claimants and, alongside the complexity of navigating the portal alone, without legal representation, it seems clear that significant numbers of claimants will be dissuaded from pursuing their claims. This is a concern with regard to genuine claimants suffering injuries compounded by a resulting lack of access to rightful justice.
Further whiplash reforms on hold
It’s with some relief in the industry that further Government reforms for whiplash claims have been put on hold. Neil McKinley, President of the Association of Personal Injury Lawyers, said some of the measures were “unfair to claimants, the vast majority of whom are genuinely injured people”.
Assistance available for RTA clients
At Prosperity Insurance we can help to streamline the process for firms dealing with RTA claims by providing ATE insurance at competitive rates with fully deferred premiums, which may help to encourage injured parties to pursue claims.
We can also help to mitigate the risks involved in the litigation process, with each claim dealt with by a team of highly experienced lawyers and underwriters.
Law firms who need support for their clients or would like to find out how our products can help with RTA-related personal injury claims should contact us for more details at 0800 524 4235, or email info@prosperityinsurance.co.uk.
Sector changes for conveyancers – the good, the bad and the opportunities
Sector changes for conveyancers – the good, the bad and the opportunities
The pressure may have eased for conveyancers now the Stamp Duty Land Tax (SDLT) holiday has ended. But demand remains high and there’s a real pressure now for conveyancers to get their house in order and to better cope with the house buying demand that’s not going anywhere anytime soon.
The housing market boom
The pandemic caused an increased focus for people on their homes, which alongside the SDLT holiday of July 2020, led to an overwhelming surge in house sales. The SDLT holiday was brought in to boost the property market and help homebuyers move, and it was so successful it was extended twice beyond its original end date of March 2021, until the end of September 2021.
Pressure for conveyancers
In June 2021 house sales jumped by 220%; the property market boomed and still is booming, with May seeing further growth in average house prices for the fourth month in a row this year. The SDLT holiday enabled 87% of movers to avoid the tax; in this respect, it was a great success. But it was, and to some extent still is, a different story for the conveyancers servicing such a buoyant home-moving market.
“Perfect storm”
Named a perfect storm for conveyancers, the boom in the property market caused the entire conveyancing system to become completely overloaded, logjammed with sales delayed by months at a time. On every level, conveyancing firms were pushed to their limit, with some even turning work away in order to protect their reputation, fearful of being unable to meet service level expectations and demand.
But, while demand went through the roof, the number of those working in conveyancing went down, due to COVID-19, other pandemic-related issues and stress. There have been stories of conveyancers working through the night, or else quitting to escape the chaos of 2020, with the end result leaving the industry with 20% less people-power to handle what was estimated to be around 300,000 more transactions.
Changes needed in conveyancing
The industry has been forced to cope with the pandemic and then an unprecedented industry boom, with a number of significant changes weathered, many of which are sticking around. Some of these changes demand an urgent change to working practices or new measures to better address and deal with demand.
Increased hybrid working risks security
Just like many other sectors, hybrid, remote and homeworking have all become the semi-norm and conveyancing is no different. But there’s an impact to be borne out by hybrid working and that’s the risk to compliance when it comes to data and security.
It is much more difficult for firms with conveyancers in hybrid-working situations, to assure the security of the systems and networks they use for holding and transacting personal and sensitive data. The recent cybersecurity breach at Simplify Group has highlighted the need for assurance on data security, as well as client confidentiality, GDPR and Solicitors Regulation Authority (SRA) obligations.
These are issues that high-compliance cloud solutions would address, yet cloud technology take-up is not universal among conveyancers, despite the added security and efficiency of workflow it would offer, not to mention peace of mind.
Need for consumer-friendly conveyancing
The more user- and consumer-friendly processes there are, the quicker the conveyancing process becomes. Practical measures such as digital signatures and case-management systems with alerts for attention and tracking of the process, via an easy-to-understand dashboard, help everyone.
The conveyancing time doubled during the SDLT holiday. Instead of taking an estimated 24 hours to answer emails, it took an estimated 72 hours. As well as saving time by managing the process, digital technology with user-friendly interfaces aids oversight and reassurance, promoting client goodwill and reducing stress.
Equity-rich home buyers keep the market buoyant
Although house price growth has slowed, it is still in double digits, and a surprisingly high 38% of consumers recently surveyed are “actively moving” or “considering a move”, despite three million more homes in the UK now being in the higher rate SDLT bracket than at the start of the pandemic and the increased pressure on household budgets. What is clear is that the demand from home movers has pushed up house prices, resulting in strong demand from equity-rich homebuyers who are now freed from the pre-pandemic daily commute to look at properties further afield.
Challenges are not over for conveyancers
As the market continues to be very busy, the biggest challenge now for conveyancers is eliminating stress for home movers by making processes quicker and more efficient, and service as responsive as possible. Ultimately, a quicker process means a greater return in fees and more room to be competitive with those fees.
Opportunity to reduce conveyancing times
Our conveyancing products provide the opportunity to help firms streamline processes for clients by reducing conveyancing times and providing policies which are easy for clients to understand and competitively priced. It’s an opportunity well-timed as home movers seek a better service than that experienced by many during the peak of the boom.
Legal issues in the conveyancing process can cause time-consuming correspondence and friction among involved parties. The use of our consumer-friendly indemnities can help to solve these issues so that conveyancers can deliver a less stressful service at a more competitive price. Our policies cover a wide range of conveyancing needs, from Breach of Planning Permission to Missing Documents, and can be quoted in seconds and issued in minutes, all via our user-friendly portal.
Building conveyancing capacity
For conveyancers who want to stay ahead and continue to offer the maximum in service and client delivery, our conveyancing products offer not just a way of enhancing the client-facing offer, but build capacity to deal with the future.
Government consultation for Fixed Recoverable Costs could have big implications for the Clinical Negligence sector
The Government’s consultation to introduce Fixed Recoverable Costs (FRCs) for injured patients’ lawyers, in cases of clinical negligence under £25,000 in compensation value, has sparked controversy.
Fixed Recoverable Costs proposal
The proposal includes, as well as introducing FRCs in cases under £25,000, streamlined ‘standard’ and ‘light track’ processes, mandatory steps for claimants and defendants, and sanctions for not adhering to the scheme.
Claims the proposal is not in the public’s best interest
While it is acknowledged that the Government proposal comes from a place of trying to save money for the NHS, and simplify claims for the public, the proposal has been widely criticised for not being in the best interests of the public, or even the NHS when it comes to learning and collaboration from cases of clinical negligence, which could be limited if less low-value claims are pursued.
The charity, AvMa (action against medical accidents), has stated: “If lawyers are unable to claim for the time they spend overcoming denials of liability, injured people will not be able to get legal representation”.
Andrew Williams, Head of Insurance at Prosperity Insurance points out, similarly, how commercial viability will be affected for the legal profession and could result in fewer low-value claims.
“The biggest implication for our clients if these proposals are implemented is they will likely have to take on less low-value claims due to the fixed timeframes and fixed-rate costs – as it just won’t be commercially viable to take on lower claims if they have a level of complexity which takes more legal hours.”
Proposed ‘standard’ and ‘light track’ for clinical negligence claims
The consultation document proposes ‘standard’ and ‘light track’ claims processes with a maximum duration of 44 and 20 weeks respectively. However, data for medical negligence claims, as of November 2021, shows that currently, the average time for a claim of under £25,000 to settle is 1.3 years.
Andrew talks about how these proposed ‘track’ times could potentially affect the viability of more complex cases.
“The average medical negligence claim under £25k currently takes over a year and the new proposal for light track is just 20 weeks maximum. It is very likely firms will only take the kinds of claims that are very straightforward. This also has the added effect of increasing the amount of screening by firms, before they can even take on clients to assess the viability of the claims.”
The positive and negative implications for consumers
The impacts on the legal professionals’ capacity to take on lower-cost cases under the proposals are clear, but The Association of Consumer Support Organisations sums up the potential implications of the proposal for consumers, which are not all in the positive when it comes to being in the public interest.
Positive implications include:
- Simplified process
- Faster speed of redress for claimants
- Certainty on costs
- Removal of secondary cost litigation
Negative implications include:
- Barriers to access to justice, as claimant law firms have said they would be less inclined to accept “borderline” complex low-value cases as not commercially viable.
- Unaffordable screening of cases
- Low value does not necessarily mean low complexity
- Lack of accountability as the patient as a consumer should be at the heart of all reforms and the narrow focus on cost may not aid patient safety
Responding to the proposal
Consultation for the proposal was closed on 24th April but responses from those working in this industry were encouraged by the Department of Health and Social Care.
The overwhelming response from claimant law firms, charities and patient organisations alike has been that the proposals would be more detrimental than helpful to claimants.
CILEX have argued that fee caps have the potential to penalise victims as even the simplest claim could require significant resourcing and evidence gathering.
Furthermore, The Association of Personal Injury Lawyers accused the government of a “breath-taking display of self-interest” and have stated that the measures proposed would put “unfair restrictions on patients, bereaved families and their representatives”.
Following this, the Government will now analyse responses and publish the consultation response document. If proposals are implemented, then those proposals will need to be approved by the CPR (Civil Procedure Rule) Committee.
Continued support at Prosperity
“While there’s not much we can do to help the outcome of the proposal, we can continue to support our clients with their screening processes and help them to obtain justice for claimants and the appropriate compensation,” says Andrew.
Any legal clients or professionals concerned by the proposed changes and how this may affect their practice, or need support with screening processes, should contact our expert medical negligence team on 0800 524 4235, or email info@prosperityinsurance.co.uk.
Business interruption insurance
Business Interruption Insurance
Business interruption cases are a relatively new area of claims for the legal profession and have mainly come about because of the recent/ongoing Covid19 pandemic.
Many businesses were forced to close their doors to trade altogether and some in various other ways meaning that they have seen a significant reduction in profit or income and together with substantially increased running costs have left many businesses struggling to stay afloat. Indeed, many businesses have also gone out of business as a direct result.
Business owners who believed that they would be covered by their business interruption policies were left in shock when their genuine losses arising from the Covid19 pandemic were rejected, and were told by their insurers that they were not covered under their policies.
However, there was light at the end of the tunnel in the recent Supreme Court judgment in the case brought by the Financial Conduct Authority (FCA) that has removed some of the many roadblocks caused by insurers denying Covid19 business interruption claims.
Whilst this judgement is a positive result for claimants in principle, it failed to address the detail in how claims should be calculated (should government grants, the furlough scheme, SEISS, bounce back loans, etc. be considered) and as a result many businesses have a much different view on what the losses actually incurred are compared to those their insurance company has offered. Whilst complaints can be lodged with Ombudsman, the sheer volume of cases mean that some businesses cannot afford to wait for the process and must resort to legal action as the fastest and sometimes only way to recover the compensation that they should be entitled to under their business interruption policy.
If you have a claimant who has attempted to negotiate with their insurer to pay out a legitimate business interruption claim and it has been disputed or rejected, your next course of action will be to issue legal proceedings against that insurer.
If you are a lawyer with clients that have a business interruption case that you would like to pursue on their behalf, you need to talk to us. We can help to find for you an After the Event insurance solution that will help to meet your clients’ needs.
If your practice is seeking a fast, simple, online facility with competitive premiums you should contact us. If you require a quotation for a policy of this type please complete the form below and email it back to us at info@prosperityinsurance.co.uk or you can call us and speak to one of the team on 0800 524 4235.
ATE
Insurance
ATE Insurance is an insurance policy that protects and covers a client who wants to pursue a claim against the risk of having to pay their opponents legal costs and disbursements if the case is unsuccessful.
Conveyancing Indemnities
As an experienced provider of ATE insurance to lawyers and their clients, we are well aware that the profession also has a need for other client-facing legal indemnities. One of the most frequent requests we get from solicitors is for legal indemnities for conveyancing transactions.